Reviewing a Kansas Uninsured or Underinsured Motorist Claim
After a Wichita crash, the first questions are who caused it, which policies apply, and what each policy covers. A driver having too little money to pay your losses does not automatically establish a UIM claim. Bring the policy documents and claim correspondence so the coverage and evidence can be reviewed together.
UM and UIM Address Different Insurance Situations
- Uninsured motorist (UM): bodily-injury protection involving an uninsured at-fault driver, subject to the policy and evidence.
- Underinsured motorist (UIM): Kansas law ties the additional coverage to the amount by which your applicable UM/UIM limits exceed the at-fault driver’s bodily-injury liability limits. Damages exceeding the other driver’s insurance alone are not enough.
For example, $100,000 in applicable UIM limits compared with $25,000 in liability limits leaves a potential $75,000 additional limit. Equal $25,000 limits leave no difference. These examples illustrate limits, not guaranteed payments. Read the Kansas requirement and limit-comparison Q&A and K.S.A. 40-284.
Documents to Bring to a Free Consultation
- Your declarations page, full policy, endorsements, and any written rejection of coverage above the minimum
- The crash-report number, photographs, video, and witness contact information
- Medical records, bills, and documentation of missed work or other injury losses
- The claim number, insurer letters, denial explanation, and any settlement offer or proposed release
You do not need every document before calling. Identify any pending insurer request or proposed settlement. Follow applicable policy notice and cooperation requirements, and obtain advice before signing a release. K.S.A. 40-284(f) sets a certified-mail notice process and a 60-day opportunity for the UIM insurer to substitute payment in a tentative policy-limits settlement with an underinsured driver.
Choose the Guide That Fits Your Question
Coverage Points to Check Carefully
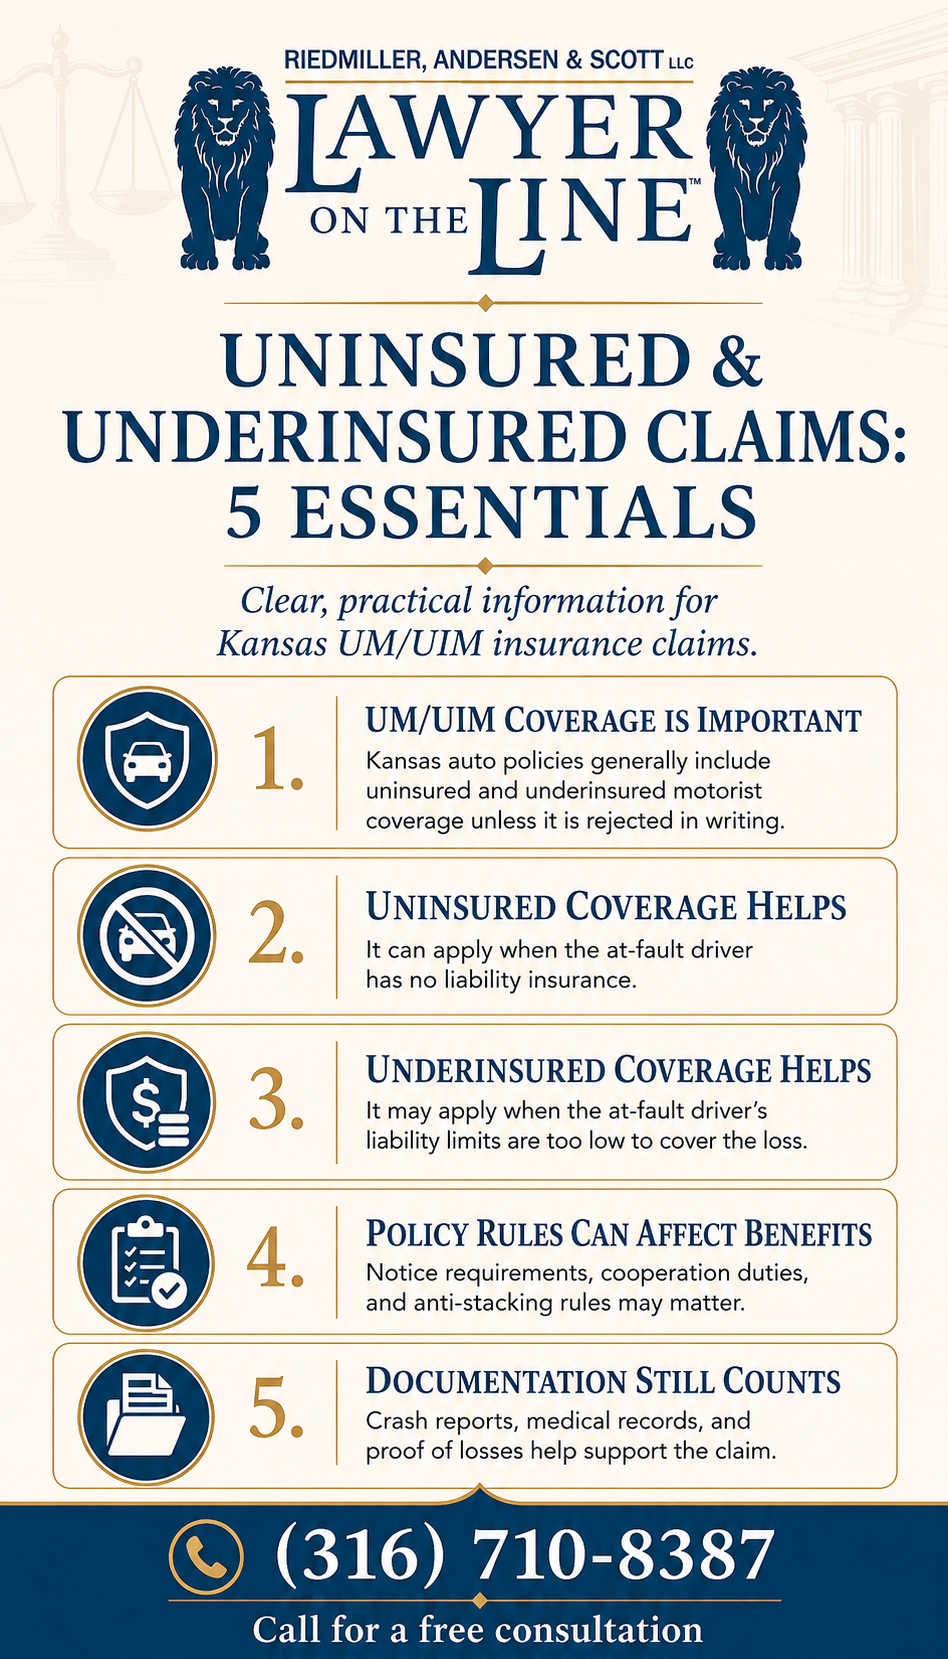
Kansas requires minimum UM/UIM bodily-injury limits of $25,000 per person and $50,000 per accident in primary policies for vehicles registered or principally garaged in the state. Coverage generally matches bodily-injury liability limits unless the named insured rejects the amount above the minimum in writing. The required minimum cannot be rejected; excess and umbrella policies are treated differently.
Multiple applicable policies cannot simply be stacked to add their limits above the highest limit of one applicable policy under K.S.A. 40-284(d). For an unidentified hit-and-run driver, the statute permits a limitation when there is neither evidence of physical contact nor reliable competent evidence from a disinterested witness who is not claiming under the policy. Preserve relevant evidence and have the actual policy reviewed.
Required UM/UIM coverage concerns bodily injury. Collision or other applicable property coverage should be reviewed separately for vehicle repairs. PIP and other benefits have their own limits and coordination rules. The Kansas Department of Insurance auto guide explains these different coverages.
Common Causes of Auto Accidents in Wichita
Motor vehicle accidents in Wichita occur for many reasons. When the at-fault driver lacks applicable insurance, the collision can also raise coverage questions. Possible causes include:
- Distracted Driving: Texting, eating, or using a GPS while driving takes attention off the road and leads to serious crashes.
- Speeding: Excessive speed can contribute to collisions, including on major Wichita roads such as Kellogg Avenue and I-135.
- Driving Under the Influence: Alcohol and drug impairment drastically reduce reaction times and decision-making abilities.
- Reckless Driving: Aggressive behaviors like tailgating, unsafe lane changes, and running red lights contribute to many Wichita accidents.
- Weather Conditions: Wichita’s winter storms and heavy rains create hazardous driving conditions, often leading to multi-vehicle accidents.
- Failure to Yield Right-of-Way: Intersection collisions are common when drivers fail to respect traffic laws.
When an uninsured or underinsured driver causes an accident under these circumstances, victims are left struggling to pay for medical bills, lost wages, and property damage without adequate insurance coverage.
Common Injuries in Wichita Car Accidents
Car accidents involving uninsured or underinsured drivers in Wichita often result in serious, life-changing injuries. Even crashes that happen at relatively low speeds can cause significant physical trauma, leading to expensive medical care, long-term rehabilitation, and lasting emotional effects.
Some of the most common injuries seen in Wichita car accidents include:
- Whiplash and Soft Tissue Injuries: Sudden, violent movement of the head and neck during a collision can strain or tear muscles, tendons, and ligaments. Whiplash is particularly common in rear-end collisions and can cause lasting pain and limited mobility.
- Broken Bones and Fractures: The force of impact can easily cause fractures to arms, legs, ribs, and hips. Severe fractures may require surgery and months of rehabilitation.
- Traumatic Brain Injuries (TBI): Concussions and more serious brain injuries can occur when the head strikes a window, steering wheel, or airbag. TBIs often result in memory loss, cognitive difficulties, and emotional changes.
- Spinal Cord Injuries: Damage to the spinal cord can lead to partial or complete paralysis, requiring extensive medical intervention and lifestyle adjustments.
- Internal Injuries: Blunt force trauma can cause internal bleeding or damage to vital organs, such as the lungs, liver, or spleen, often requiring emergency surgery.
- Psychological Injuries: Beyond physical harm, victims may suffer from post-traumatic stress disorder (PTSD), depression, or anxiety after a serious Wichita car accident.
At Riedmiller, Andersen & Scott, we recognize that the full impact of a Wichita car accident often goes beyond immediate injuries. Documenting treatment, symptoms, missed work, and other losses helps evaluate the bodily-injury claim. Payment depends on the evidence, applicable law, and available coverage.
Determining Liability in an Uninsured and Underinsured Motorist Accident
In a Wichita UM/UIM case, proving who was at fault is still critical. Even when making a claim under your own policy, your insurance company may require clear evidence that the uninsured or underinsured driver caused the accident.
Key elements used to determine liability include:
- Police Reports: Accident reports prepared by law enforcement provide valuable documentation of fault.
- Witness Statements: Eyewitness accounts can support your version of events.
- Surveillance Footage: Traffic cameras and security systems near the accident scene may capture critical evidence.
- Vehicle Damage Analysis: The type and location of damage can reveal how the crash occurred.
- Accident Reconstruction Experts: In serious cases, experts may be needed to analyze crash data and recreate the events leading up to the collision.
Even though you may be filing a claim under your own UM or UIM coverage, your insurance company acts as an opposing party and they may try to minimize the payout. An attorney can review the applicable policy, evaluate the evidence, and address the insurer’s stated coverage or valuation concerns.
When Does UM/UIM Insurance Apply?
Depending on the policy, insured status, and evidence, UM/UIM questions can arise in situations including:
- Accidents with Uninsured Drivers: When the at-fault driver has no insurance at all.
- Hit-and-Run Accidents: If the driver is unidentified, review physical-contact evidence or reliable competent evidence from a disinterested witness who is not claiming under the policy, as well as the policy terms.
- Underinsured Drivers: When applicable UM/UIM limits exceed the at-fault driver’s bodily-injury liability limits and the claim otherwise qualifies.
- Pedestrian and Bicycle Accidents: If you are hit by an uninsured driver while walking or biking in Wichita, UM/UIM coverage may still apply.
- Passenger Claims: If you were a passenger in a vehicle involved in a crash with an uninsured or underinsured driver, you may be covered under your own or the driver’s UM/UIM policy.
The applicable limit is a ceiling, not a promised payment. Fault, covered losses, policy terms, and other relevant benefits affect the claim.
How Can an Attorney Help After a UM/UIM Accident in Wichita?
A UM/UIM claim can involve disagreements over coverage, fault, injury causation, or the amount of damages. Review the insurer’s actual explanation alongside the policy and evidence.
An experienced Wichita uninsured and underinsured motorist attorney can make a critical difference by:
- Reviewing Your Policy: We carefully analyze your insurance coverage to determine the full extent of your UM/UIM benefits, identify exclusions, and clarify what compensation you are entitled to claim.
- Investigating the Accident: Our attorneys gather and preserve critical evidence, including police reports, witness statements, accident scene photos, and vehicle damage assessments, to clearly establish fault.
- Documenting Injury Losses: Medical bills, lost income, rehabilitation needs, and pain and suffering may be relevant to a bodily-injury claim. Vehicle repairs should be considered under separate applicable property coverage.
- Negotiating with Insurance Companies: Insurance carriers often offer low settlements in UM/UIM cases. We fight aggressively on your behalf to demand fair compensation that accurately reflects the true extent of your damages.
- Filing a Lawsuit if Necessary: If negotiations fail, we are fully prepared to take your case to court. Our team builds strong cases designed to stand up to insurance company tactics and succeed at trial if needed.
At Riedmiller, Andersen & Scott, we understand the overwhelming stress that Wichita victims face after being hit by an uninsured or underinsured driver. Our attorneys work tirelessly to lift that burden and fight for your financial security. We stand by victims of car accidents in Wichita and also offer invaluable legal support in many other areas of life, including:
If you have lost a loved one in a Wichita car accident, our team is here to help you pursue a
wrongful death claim. We offer free, no-obligation consultations to injured victims in Wichita. If you have been injured or lost a loved one in an accident, call us today or connect with us online to speak with a trusted attorney.
What Compensation Is Available After a UM/UIM Accident in Wichita?
A covered UM/UIM bodily-injury claim may involve the following losses, subject to fault, evidence, policy limits, and applicable coverage conditions:
- Medical Expenses: Documented accident-related treatment and supported future medical needs.
- Lost Wages: Recovery for income lost while you were unable to work due to your injuries, including missed bonuses, overtime, and other employment benefits.
- Loss of Future Earning Capacity: If your injuries permanently impact your ability to work, you may be compensated for the loss of future income and career opportunities.
- Pain and Suffering: Compensation for the physical pain, emotional distress, mental anguish, and trauma resulting from the accident and its aftermath.
- Vehicle Damage Is a Separate Coverage Question: Required Kansas UM/UIM coverage is bodily-injury coverage. Review collision or other applicable property coverage for repairs, replacement, and any deductible.
- Loss of Enjoyment of Life: Damages for the loss of ability to participate in hobbies, sports, travel, and other activities that were an important part of your life before the accident.
- Permanent Disability or Disfigurement: Compensation for catastrophic injuries that cause lasting impairments, such as amputations, scarring, or paralysis.
Every UM/UIM claim is different, and the amount of compensation available depends on the details of the policy, the severity of the injuries, and the impact on your life. Records and, when appropriate, qualified expert opinions may help evaluate the claim. Ask at your consultation which evidence needs attention in your case. Whether you were involved in a hit & run, a serious
rollover accident, or a fender bender, our team is here to help you claim your rightful compensation.
Contact Riedmiller, Andersen & Scott After a UM/UIM Accident in Wichita
If you or a loved one has been injured in a Wichita accident involving an uninsured or underinsured driver, you do not have to handle the legal and financial burden alone. Time is critical, as insurance companies may impose strict deadlines for filing UM/UIM claims.
Bring your policy, crash records, insurer letters, and any proposed settlement to discuss your options. Riedmiller, Andersen & Scott, LLC offers free consultations and contingency-fee representation. Ask about attorney fees, case expenses, and the written agreement before hiring the firm.